


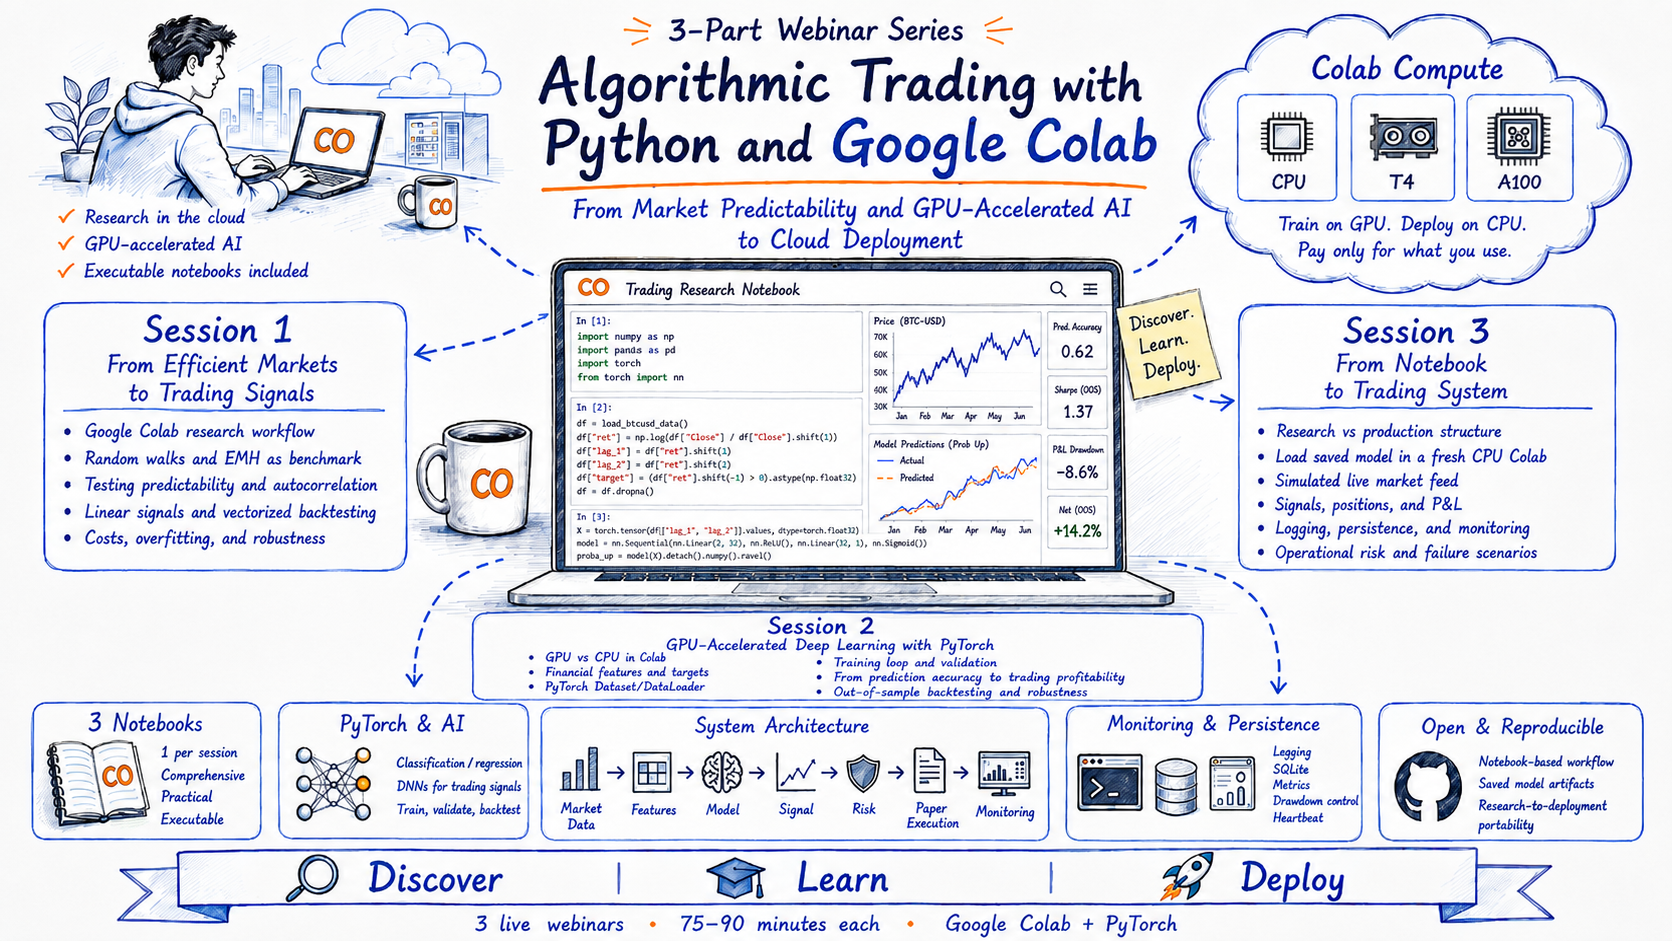
This repository contains the complete companion code and interactive Jupyter notebooks for the three-part webinar series on Algorithmic Trading with Python and Google Colab, presented by Dr. Yves J. Hilpisch (The Python Quants GmbH).
The curriculum bridges quantitative finance theory and auditable paper-trading across three core pillars: Discover (hypothesis testing and EMH) → Learn (GPU deep learning with PyTorch) → Replay (SQLite persistence, operational risk, and reconciliation).
Each notebook is completely self-contained and pre-configured to run directly in Google Colab with zero local installation:
| Session | Topic | Key Concepts | Colab Link |
|---|---|---|---|
| Session 1 | Can Markets Be Predicted? | EMH benchmark, random walk null model (GBM), return autocorrelation, Ljung-Box test, linear OLS signal model, vectorized backtesting with transaction costs. |  |
| Session 2 | Teaching a Neural Network to Trade | Colab GPU tensor acceleration, quantitative feature engineering, multi-layer TradingDNN in PyTorch, cross-entropy vs economic Sharpe, confidence thresholding, model capacity analysis. |
|
| Session 3 | From Notebook to Trading System | Exact checkpoint loading, batch/stream parity, historical event replay, SQLite audit trail, failure injection, drawdown flattening, and reconciliation. | |
.
├── README.md                           # Repository documentation & Colab access
├── requirements.txt                    # Core scientific & deep learning libraries
├── notebooks/                          # Standalone Jupyter Notebooks
│   ├── 00_colab_introduction.ipynb
│   ├── 01_can_markets_be_predicted.ipynb
│   ├── 02_deep_learning_gpu_trading.ipynb
│   └── 03_cloud_deployment_monitoring.ipynb
├── src/                                # Modular Python trading system code
│   ├── data.py                         # Historical data loader & lagged feature engine
│   ├── models.py                       # PyTorch TradingDNN & training loop
│   ├── backtest.py                     # Vectorized backtester & performance analytics
│   ├── artifacts.py                    # Checksummed Drive run bundles
│   ├── config.py                       # Shared experiment configuration
│   ├── session1.py                     # Session 1 experiment orchestration
│   ├── session2.py                     # Session 2 model/evaluation orchestration
│   └── session3.py                     # Session 3 replay orchestration
└── data/                               # Sample datasets
    └── eod_data.csv                    # Historical EOD prices (SPY, EURUSD, BTC, etc.)
If running locally instead of Google Colab:
git clone https://github.com/yhilpisch/algocolab.git
cd algocolabpython3 -m venv venv
source venv/bin/activate
pip install --upgrade pip
pip install -r requirements.txtRun the participant notebooks in order. In Colab, Session 1 creates the Drive run bundle, Session 2 adds the model contract, and Session 3 performs the auditable paper-trading replay.
The bundled data/eod_data.csv is the frozen teaching snapshot. Its source is:
https://hilpisch.com/eod_data.csv
The material, code, and notebooks in this repository are provided for educational, informational, and personal research purposes only. They do not constitute financial, investment, legal, or professional advice, nor do they represent an offer or solicitation to buy or sell any security, financial instrument, or trading strategy.
Past performance, whether simulated, backtested, or real, is no guarantee of future results. Algorithmic trading and financial market investments carry substantial risk, including the possible loss of principal capital. You are solely responsible for evaluating the merits and risks associated with any decisions made based on this software or material.
All materials and code are protected by copyright.
© Dr. Yves J. Hilpisch | The Python Quants GmbH
Website: https://tpq.io | https://hilpisch.com
This code is licensed for personal, non-commercial use only. No part of this repository may be reproduced, republished, or utilized in commercial products, services, or paid training without prior written permission from The Python Quants GmbH.